Kemcore’s Botswana Critical Minerals Play is about Factories, not More Mines.
A new Chemical Plant Development in Botswana Highlights the Changing Supply-Chain Landscape that is Driving more investment in Africa
New Chemical Plant Planned for Botswana
New Chemical Plant Announced
This week has seen a new chemical factory development in Botswana get the green light. There is however, a much wider story that illustrates how global supply-chain disruptions are starting to drive further developments in manufacturing in Africa.
Kemcore’s environmental clearance for a $140 million chemicals plant in Botswana is being filed and finalised. In most news coverage, this has been framed as another critical-minerals topic.
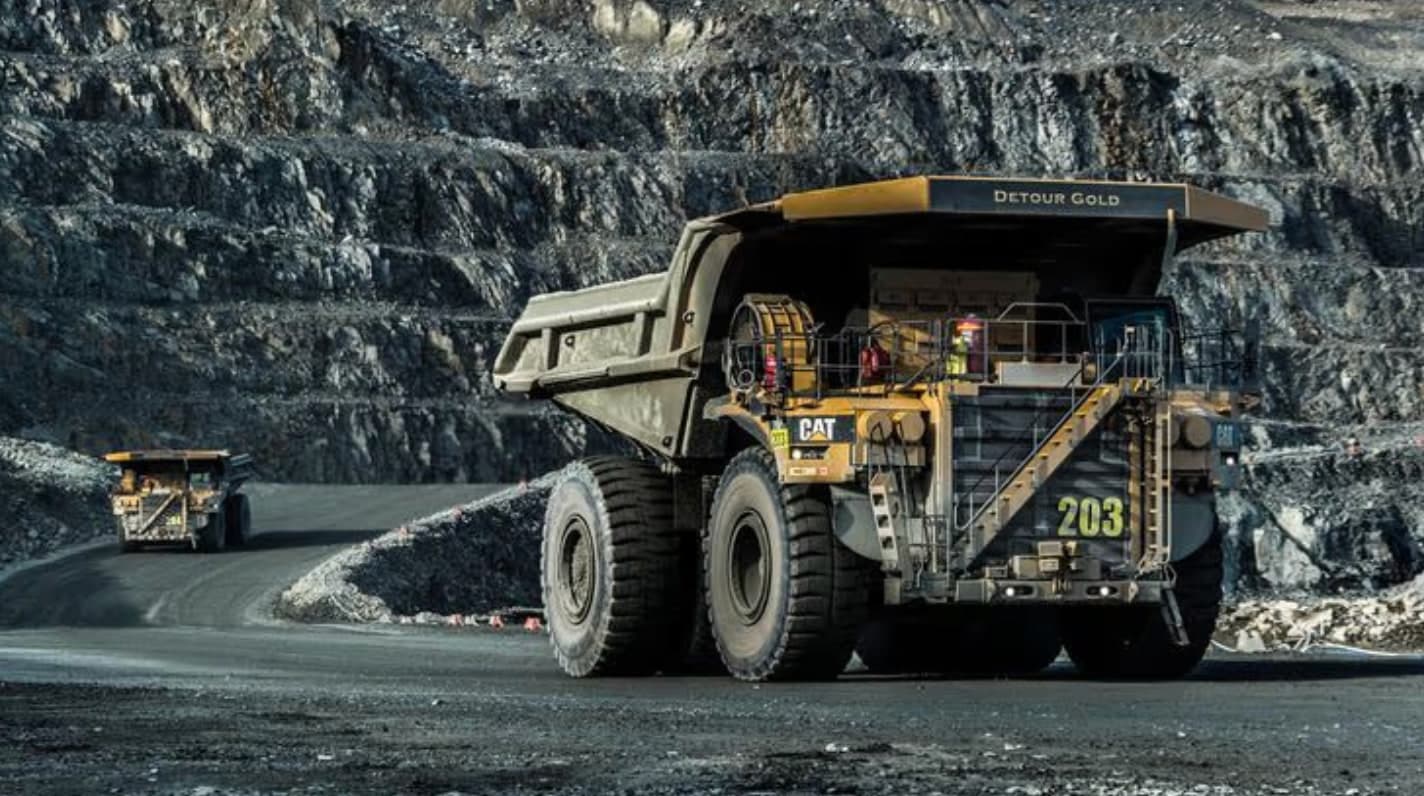
That is however the wrong framing. The real story is that the company is not sinking capital in central Botswana to extract more copper or cobalt. It is building a factory to make the reagents African mines already burn through every day, and to do it next to the Copperbelt rather than on a ship that has to clear a choke point.
No Mine Equity Required for Critical Mineral Investment
Founder and chief commercial officer of Kemcore, Calisto Radithipa, has said the plant will produce sodium metabisulphite, sodium hydrosulphide and sodium isobutyl xanthate for copper and cobalt operations in the Democratic Republic of Congo and Zambia.
Financial close is targeted for December 2026, construction in 2027, first output in the first half of 2028, with about 150,000 tonnes a year once fully ramped.
The site sits inside Botala Energy’s planned Leupane Energy Hub, close to gas, soda ash and salt. Talks with regional and local funders are advanced, Radithipa told Reuters, because the project offers exposure to the battery-minerals boom without putting equity into a mine.
African Made Products for Africa
That last point highlights the commercial logic. Kemcore is not doing this as industrial policy theatre. African mines already import a large share of the chemicals they use from China and the Middle East. Those supply lines have been thinning.
Earlier this year Radithipa pointed to sulphur disruptions and a premium on sulphuric acid at Dar es Salaam after the Iran conflict interrupted shipments. This week’s market brief made the same point in another commodity: the Iran–US war has taken an estimated 36 million tonnes of LNG off the global market, almost equal to Africa’s entire 2025 LNG export volume, and Asian spot prices have jumped toward levels last seen in late 2022.
The lesson travels across industries. When a reagent, a fuel or a spare part has to cross a strait, a canal or a single foreign factory, African production stops when that line snaps.
Location Location Location
The old adage of property investments holds fast when looking at the global supply-chain industry.
A plant in Botswana that feeds Ndola and Kolwezi shortens that line. It does not remove geopolitics. It changes who sits on the wrong side of it.
The same pattern is showing up in the energy sector. This week Aliko Dangote said construction of a $17 billion refinery at Lamu, Kenya, is due to start by the end of September, with a three-year build and East African governments circling equity. Nairobi is also talking to the group about an 800-kilometre pipeline from Turkana to the coast. That project will have its own funding and crude-supply risks.
The direction is still clear: process fuel where it will be burned, instead of paying freight and foreign refiners for the privilege of importing finished product.
Angola and Namibia are pushing the other end of the same idea, accelerating offshore oil and gas work so that molecules produced on the Atlantic seaboard do not have to leave the continent as crude and return as diesel.
Moving Africa from a Quarry to a Quality Product Provider
Put those three together and the picture is not “Africa as a quarry.” It is Africa as a cluster of midstream plants sitting next to the customers who already exist. Mines in the Copperbelt need reagents. Truck fleets and power plants need fuel. Farms need fertiliser. Cement plants need gypsum and additives.
For two decades the default answer was import. The new default, if these projects hold, is "make it here" - because the imported version is late, expensive or missing.
Developments in Rail will Support Manufacturing
Rail is the piece that makes the factory arithmetic work. The Lobito Corridor is already moving Congolese copper to Angola’s Atlantic coast. The Lobito Atlantic Railway drew about $300 million from a $753 million package in June and is planning a sharp lift in volumes.
The longer Zambia–Angola greenfield section is still years from carrying paying tonnes. Even so, a chemicals plant in Botswana that can put product on road and, later, rail toward the Copperbelt is a different business from a trader waiting on a container in Durban or Dar es Salam. Pan-African corridors will not erase borders. What the will do, is to change the cost of serving a regional market from a single factory.
Development Promise Must become Delivery
None of this is charity, and none of it is guaranteed. Environmental clearance is not a funded plant. December's close can slip. Gas from Botala’s coal-bed methane project has to arrive. Soda ash and salt from Botash have to be contracted at a price that leaves margin after freight to Zambia and the DRC.
Offtake from the mines has to be real, not a slide. Dangote’s Lamu complex still has to lock crude and capital. Namibia’s and Angola’s wells still have to produce. African manufacturing has a long record of announcements that never poured concrete.
What has however changed, is the penalty for not building. A war in the Gulf, a Chinese export control or product supply squeeze, a congested port or a currency spike used to be an inconvenience. For a Copperbelt mill that cannot run without SMBS or xanthate, it is downtime. For a haulage firm that cannot buy diesel, it is parked trucks. That is why funders who will not touch a mine will look at a chemicals plant: the demand is already in the ground, the product is consumed on site, and the alternative supply is now politically noisy.
Rinse and Repeat to Accelerate Growth
If Kemcore reaches first production in 2028, the interesting question will not be whether Botswana has “joined the critical-minerals race.” It will be whether a second and third factory follow in the same logic: reagents, explosives, grinding media, filters, specialised lubricants, packaging, spare parts.
Those are unglamorous products. They are also the products African industry actually buys. A continent that only ships concentrate will always be a price-taker on both the way out and the way back in. A continent that makes the inputs its own mines and plants consume starts to keep the margin that used to leak through the port.
That is the milestone that needs to be reached for. A bet that the new normal for African supply-chains is shorter, possibly uglier, but far more importantly, closer to the customer. Because the long, elegant import route has in the new supply-chain world become the risky one.